Wealth Protection & Planning
Learn What Your Money Is Doing Before You Retire
Get a clear, simple look at the money you have saved and the plans you already have. You will see what is working, what is not, and what you can do next.
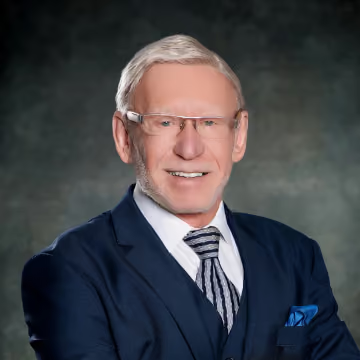
Jeff Altman
- Owner/Operator/Advisor
My passion is simple: increase your wealth while protecting your wealth at the same time, for one critical objective, to fulfill and optimize your deep personal goals, desires, and dreams. It is all about you, your values, your principles, your mission, and your life's quest for personal achievement. I've retired well three times, and I keep coming back because continuing my career energizes me and keeps me vital. Helping my clients is my ultimate concept of success.
Certifications and affiliations shown above, see the disclosures page for what each one means and who issues it.
What Can Quietly Undo Your Retirement
Most people don't lose their retirement to one big mistake. It's the things nobody explained to them along the way.
An IUL With Fees You Were Never Shown
You bought an indexed universal life policy because someone told you it would grow your money and protect it from market losses. But if your agent never walked you through the fees, or how they affect what you actually keep, you have no way to know if it's working. We'll show you exactly what's happening inside your policy, in plain language.
An Annuity Locked Behind Surrender Charges
Many annuities carry surrender charges of 7-9% if you move your money before the term is up, which can trap you in a product that isn't performing the way you were told. In many cases, a carrier bonus can offset or exceed that charge when you move to a better fit. We'll walk through the real, current numbers with you before you decide anything.
A 401(k) With No Real Downside Protection
What if the market dropped about 38%, the way it did in 2008? A 401(k) has no floor underneath it, so a drop like that is yours to absorb, and the people closest to retirement absorb it the hardest. Every dollar you eventually withdraw, principal and growth alike, is taxed as income on top of that. Nobody can tell you when the next correction arrives. What you can decide now is whether you want your principal protected before it does.
How We Help You Protect What You've Built
We start with an honest review of what you already have, an IUL, an annuity, a 401(k), before ever talking about anything new. From there, we build a plan around your real goals, not a generic number.
IUL Rescue
A Full Fee Review
We go through your existing policy in plain language, so you can see what's being charged and how it affects your growth over time. If your original agent never walked you through this, we will.
Is It Structured Right?
Some IULs are set up well. Others are trapped with high fees from day one because of how they were originally sold. We'll give you an honest read on which one you have.
A Second Opinion, No Pressure
If your policy is genuinely working, we'll tell you to leave it alone. We only recommend a change when it actually improves your position.
Annuity Rescue
Real Performance vs. What Was Promised
We compare what your annuity is actually earning against what you were told when you bought it, and against what a surrender charge would cost you to move.
Offsetting a Surrender Charge
Many carriers offer a bonus to move your funds into a better-performing product, one that can offset or exceed a surrender charge. We'll walk through your real, current numbers before you decide anything.
You Decide, We Don't Push
This is a review, not a sales call. You'll leave with a clear picture either way.
Retirement + Income Planning
A Plan Built Around Your Goals
Not a generic number to hit. We build your retirement plan around your actual goals, your family, and the life you want it to fund.
Making One Dollar Do Double Duty
One family we worked with built a full six-year college fund for their kids alongside their retirement savings, without adding new out-of-pocket cost. We look for the same kind of overlap in your own plan.
A Second Look at Your 401(k) or IRA
Most 401(k)s offer no protection if the market drops, and every dollar you withdraw gets taxed as income. We'll show you where that gap is and what your real options are.
Your 3-Step Path to a Confident Retirement.
A Free Conversation
Book a 30-minute call with Jeff directly. No cost, no obligation, just a real conversation about your situation.
An Honest Review
We look at what you already have, an IUL, an annuity, a 401(k), and tell you plainly whether it's working.
A Plan Built Around You
If we can improve your position, we'll show you exactly how. If we can't, we'll tell you that too.
Meet the Team
A group of specialists Jeff works with directly, in mortgage planning, tax, Medicare, and estate law, so your situation gets handled by the right person, not a generalist.
Jeff Altman
Owner/Operator/Advisor
Read Bio
George Bain
Mortgage and Creative Financing Expert
Read Bio
Sean Farrell
Advisor
Read Bio
Joe Clark
CFEd®
Read Bio
Arlene Schaeman
Medicare Specialist
Read Bio
Robert Stovall
Tax Professional
Read Bio
Paul Himmelstein
IRA Conversion Specialist
Read Bio
Jennifer Surmacz
President and Chief Counsel, Posterity Legal Services, LLC
Read Bio
James Jurica
Investment Advisory Services, Wealth Watch Advisors
Read Bio
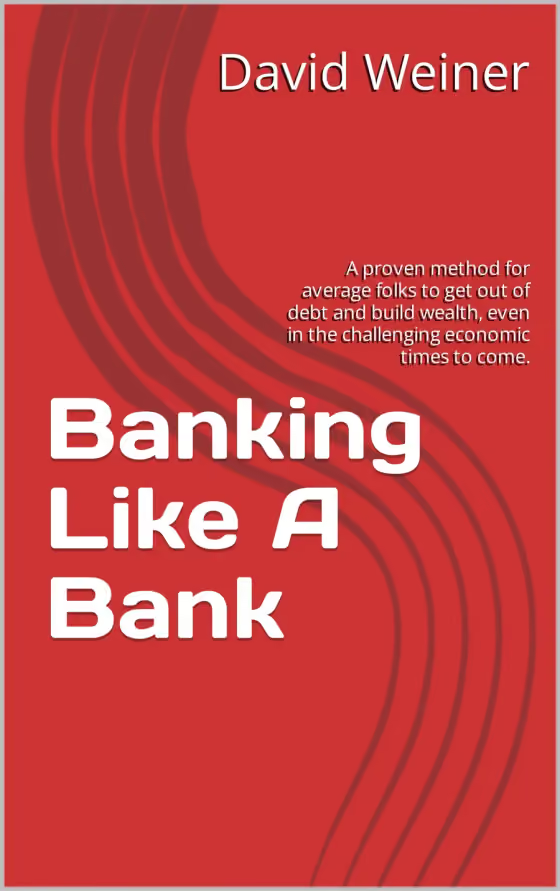
Banking Like a Bank
The book on becoming your own source of financing
Banks make their money lending out other people's money. This book makes the case that you can do the same thing for yourself, financing your own major purchases, education, or supplemental income instead of handing a bank the profit. It runs about 85 pages, so it's a short read, and most people finish it with more questions than they started with. Those questions are what the call is for.
Common Questions
A few of the questions we hear most, see the full FAQ for everything else.
I already have an IUL, can you help?
Yes, that's exactly what IUL Rescue is for. We'll go through your existing policy together and look at the actual fees, how it's structured, and whether it's performing the way you were told it would. If it's working well, I'll tell you to leave it alone. If it isn't, we'll walk through what your real options are, no pressure either way.
Learn about IUL Rescue →Are annuities bad?
You've probably read the bad press. The honest answer is that there are bad annuities. An annuity is a sophisticated instrument, and it has to be tailored to your needs and your goals to be worth owning. Built well, one can offer tax-deferred growth, protection from market losses, and, depending on the product and its riders, income for life backed by the claims-paying ability of the issuing insurance company. Built badly, it's an expensive product someone sold without ever explaining the fees or the surrender schedule. So ask a narrower question: was the annuity you have right for you, or was it right for the agent who sold it to you?
How are you paid?
I'm paid by the insurance carriers I work with, out of their own margin, never billed to you directly. That's a normal, disclosed part of how insurance products are sold. You make money, the carrier makes money, and I make money, with nothing hidden about how that works. There's no fee for a call or a policy review either way.
Are you licensed in my state?
I work with clients nationwide, not just in one state. If you're outside a state where I'm currently licensed, I can typically obtain the license needed within a short time before we move forward with anything. Reach out and we'll confirm your specific state on the call, before any product or policy discussion starts.
What happens on the free call, is there any obligation?
A 30-minute call with me costs you nothing, I'm compensated by the insurance carriers I work with, never by you directly. There's no obligation and no sales pressure. I'll walk through your situation, answer your questions, and let you decide what happens next.
Get in touch →What is an IUL?
IUL stands for indexed universal life. It's a permanent life insurance policy with a cash value inside it, where the interest credited to that cash value is tied to the performance of a market index such as the S&P 500 instead of being invested in the market directly. Because you don't own the index, a falling index doesn't subtract from your cash value, and a rising one credits interest subject to caps and participation rates that limit how much of the gain you receive. Policy charges come out either way, every year, which is exactly why how the policy was built determines what you actually keep. If you'd like to understand how one works, or how the one you already own works, call Jeff and he'll walk you through it.
Learn about IUL Rescue →Why don't you work with securities?
Because of what is at stake for the person in front of me. I believe someone at or near retirement should not have to risk the principal they spent a working life building. Warren Buffett is often quoted on his rules for investing: rule one, do not lose principal; rule two, refer to rule one; rule three, refer to rules two and one. That is the standard I hold the money you have already saved to. So I work with insurance products whose guarantees are spelled out in the contract and backed by the claims-paying ability of the company that issues them, and I show you what is guaranteed and what is not before you decide anything. I am not registered to sell securities or to give investment advice, and I will say so plainly rather than stretch to fit. If a securities portfolio is what you want, you want a licensed investment professional for that, and I will tell you so.